

Business
Big Tech’s AI Boom Is Hiding Hundreds Of Billions In Financial Risk
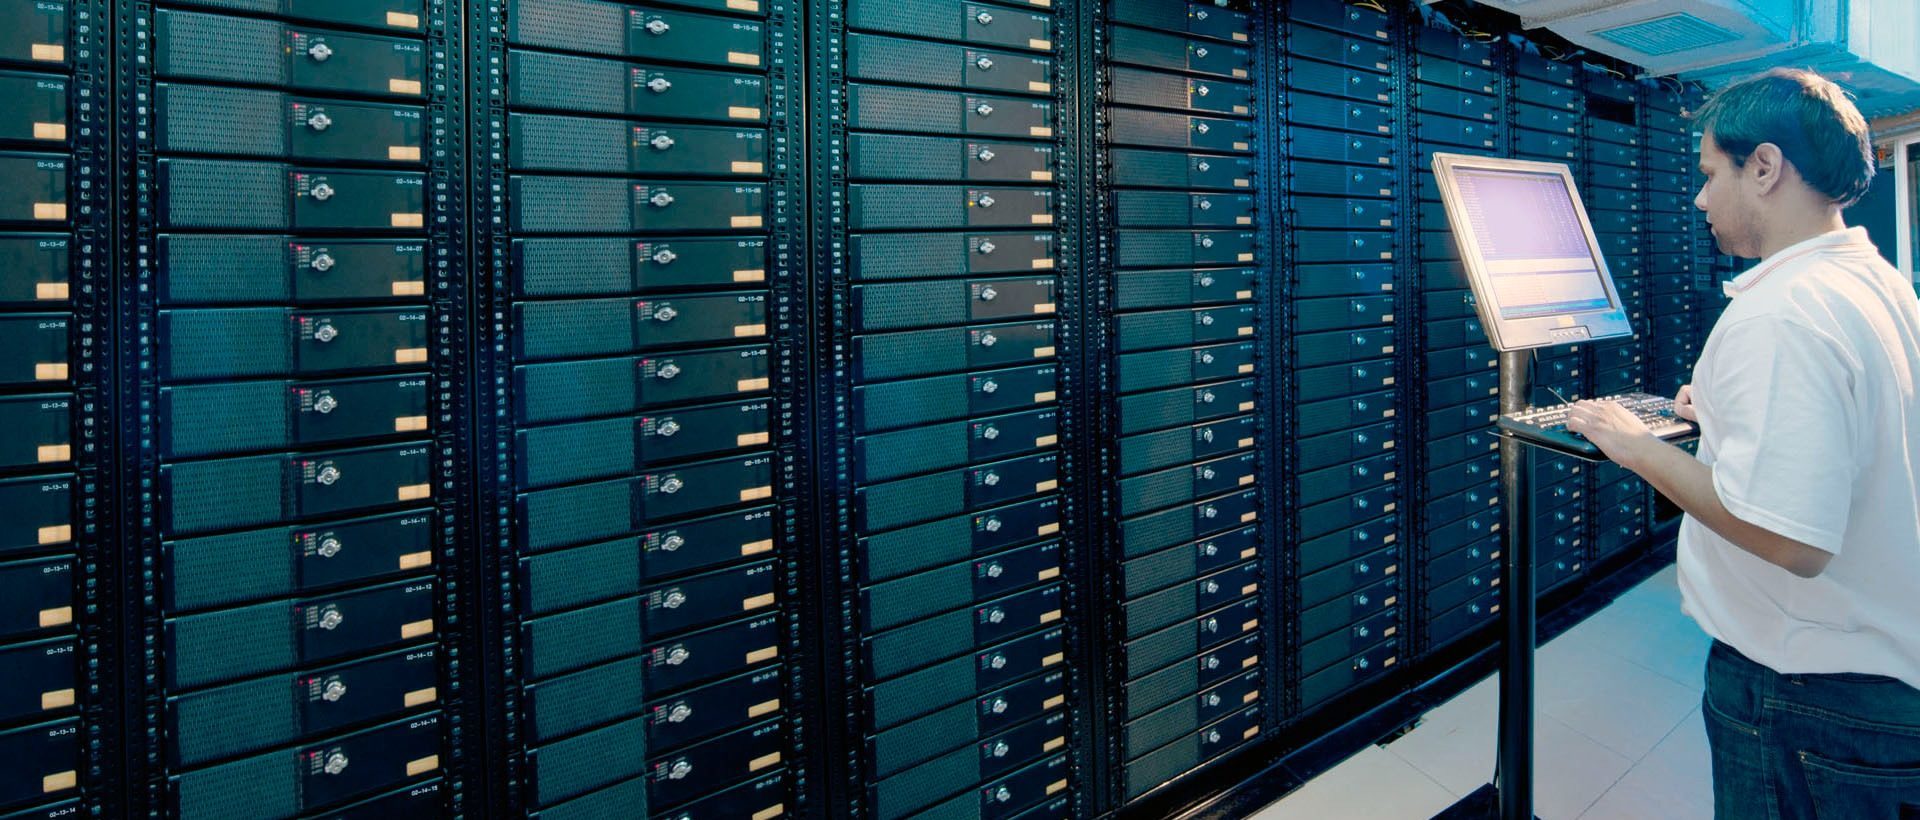
Data center (Azraelito/Wikimedia Commons)
Big Tech companies are using hundreds of billions of dollars in guarantees to finance the artificial intelligence boom while keeping much of the exposure from appearing as conventional debt on their balance sheets.
Technology companies issued as much as $300 billion in guarantees tied to AI data centers and chips over the past year, according to a Financial Times analysis. The structures are helping companies fund massive infrastructure projects without taking on the full balance-sheet burden of financing them directly.
The arrangements, known as residual value guarantees, typically involve a technology company promising that chips, data centers or other infrastructure will retain a minimum value in the future. If the assets are later sold or leased for less than that amount, the company providing the guarantee could be responsible for part of the difference.
The financing has become increasingly attractive as technology companies race to secure computing capacity while trying to preserve their investment-grade credit ratings and access to relatively cheap corporate debt.
Morgan Stanley analysts estimated seven major cloud and semiconductor companies accumulated more than $3.1 trillion in off-balance-sheet commitments and other forms of credit support.
S&P Global Ratings separately warned that special-purpose vehicles, vendor financing, backstop agreements and residual value guarantees can “increase debt-like exposure, obscure risk, and create financial interdependencies.”
The guarantees generally back debt issued by special-purpose vehicles rather than the technology companies themselves. Those entities own the chips or data centers, allowing Big Tech companies to support the financing without immediately recording the entire obligation as debt.
Broadcom took on roughly $29 billion in exposure in June as part of a deal involving chips that will ultimately be leased to Anthropic. The financing arrangement was developed alongside Google as part of a broader effort to supply computing infrastructure to the AI company.
Broadcom told investors it believed the guarantees were unlikely to be triggered because of the profitability of major AI developers and the expected value of the assets backing the financing.
Nvidia has increasingly embraced similar arrangements. The chipmaker said it could provide residual value support covering as much as 25% of certain infrastructure financing deals being assembled alongside Goldman Sachs and other major investment firms seeking to mobilize more than $500 billion for Nvidia-powered AI projects.
Nvidia also provided roughly $105 billion in guarantees to SB Energy, a SoftBank subsidiary developing a large Ohio data center campus for OpenAI, according to the Financial Times.
The agreement allows Nvidia to avoid immediately recording a liability tied to the project. OpenAI’s leases are expected to begin in 2028, while the data center campus is expected to use Nvidia hardware for decades.
Meta was among the first major technology companies to use the structure at scale, providing a roughly $28 billion guarantee supporting its Hyperion data center joint venture with Blue Owl in Louisiana.
The project is expected to span roughly 4 million square feet and eventually consume enough electricity to power about 1.5 million homes.
The guarantee helped the project raise roughly $27 billion in debt at borrowing costs only modestly above Meta’s own bonds while leaving relatively little exposure directly recorded on the company’s balance sheet.
The structures can lower borrowing costs because lenders have some protection if rapidly advancing technology causes chips or data centers to lose value faster than expected.
That protection could become more important if the AI boom slows.
Technology companies could face greater exposure if demand for computing power disappoints, companies build more data-center capacity than customers need or newer chips make existing hardware obsolete faster than expected.
Credit-rating agencies already attempt to account for some of the risk.
S&P Global analysts estimate how much the guaranteed value of an asset exceeds what the infrastructure could fetch during a distressed sale and can add that difference to a company’s adjusted leverage.
Pierre Georges, S&P Global’s head of infrastructure research, told the Financial Times that the largest gap he had seen between a guaranteed value and the stressed value of the underlying assets was about 25%.
That would translate into roughly $5 billion of additional adjusted liabilities on a $20 billion financing structure.
So far, rating agencies generally believe the underlying assets retain enough value to cover much of the financing.
The larger test will come if the enormous investment in AI infrastructure fails to generate the revenue companies are expecting.
As technology companies increasingly turn to guarantees and other off-balance-sheet structures to fund the buildout, the amount of debt appearing on their balance sheets may tell only part of the story about how much financial risk they are taking on.
All content created by the Daily Caller News Foundation, an independent and nonpartisan newswire service, is available without charge to any legitimate news publisher that can provide a large audience. All republished articles must include our logo, our reporter’s byline and their DCNF affiliation. For any questions about our guidelines or partnering with us, please contact [email protected].